Adam Smith, trusted institutions and Canada’s European opportunity
By Dr. Brian O’Donnell | Aurex Insights
In 1917, amid the destruction of Vimy Ridge, a Canadian soldier named Leslie Miller gathered acorns from the battlefield and carried them home to Ontario. They took root. A century later, cuttings from those Canadian oaks were returned to France and replanted at Vimy Ridge.
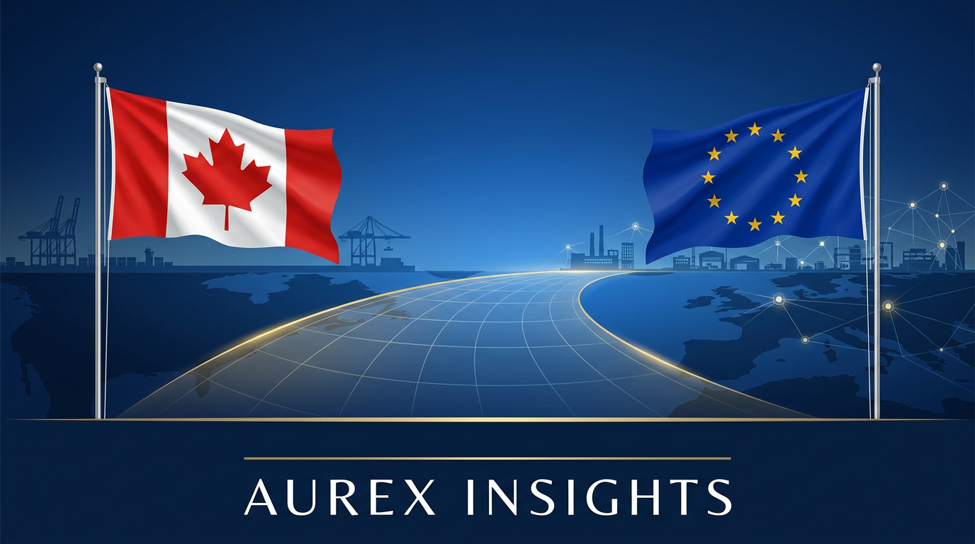
Mark Carney recalled that story in his address to the European Parliament last week. It is more than a gesture of remembrance. It captures something real about the Canada–Europe relationship: ties formed in shared sacrifice, sustained across distance, and renewed when circumstances demand more than sentiment.
But history and goodwill, however valuable, are not investment strategies.
A company deciding whether to build a critical-minerals refinery, finance a transmission link, expand a defence-production line or establish a European manufacturing base does not begin with a diplomatic communiqué.
It begins with harder questions.
- Can the project be approved on a credible timetable? Will the rules still apply after capital has been committed? Can the business secure reliable energy, hire the people it needs, move goods efficiently across borders and sell into a predictable market? If the commercial or political environment changes, is there a credible and workable way to resolve the dispute?
Those questions are not peripheral to investment.
They are investment.
Capital does not commit to optimism. It commits to confidence: confidence that contracts will be honoured; that approvals will not become interminable; that regulatory requirements will be intelligible; and that the commercial terms of a project will not be rewritten after the money has been spent.
That is why European Commission President Ursula von der Leyen’s proposal that Canada become the European Union’s first “associate member” deserves more than a ceremonial welcome.
It is an important political signal. It suggests that Canada is no longer viewed merely as a friendly trading partner across the Atlantic, but as a potential participant in a deeper European economic-security relationship – one spanning trade, investment, energy, critical minerals, advanced manufacturing, technology, defence, Arctic security and strategic resilience.
But it should be judged with clear eyes.
“Associate membership” is not yet a functioning economic architecture. Its legal basis, practical obligations, market-access implications, governance arrangements and timetable have not been defined. The announcement is not an operating model ready for Canada to accept. It is an invitation to construct one.
That uncertainty is not a reason for Canada to dismiss the opportunity.
It is a reason for Canada to define it.
The central question is not whether Canada can acquire an attractive new institutional label. It is whether Canada and Europe can build a trusted economic environment in which businesses can invest, researchers can collaborate, skilled people can move, and strategic goods can be produced and traded with greater confidence.
What matters is not the grandeur of the title. It is whether a Canadian company can more easily bid, build, hire, finance, insure and export in Europe – and whether European capital and firms can do the same in Canada.
The answer lies less in the symbolism of associate membership than in a much older insight about how prosperity is created.
Adam Smith’s deeper argument
Adam Smith is often reduced to caricature: the invisible hand, individual self-interest and a general preference for smaller government.
Smith was indeed an advocate of commerce, competition and freer trade. But his deeper concern was more ambitious. He wanted to understand why some societies create conditions in which people can specialize, invest, exchange and improve their circumstances over time, while others remain poor, insecure and politically trapped.
His answer was institutional.
Commerce requires more than willing buyers and sellers. It requires order, security, enforceable commitments, limits on arbitrary power and a system in which people can reasonably expect to retain the gains from their effort.
The celebrated Smithian formulation, recorded by Dugald Stewart from Smith’s 1755 lectures, was that little else was required to move a country “from the lowest barbarism to the highest degree of opulence” than “peace, easy taxes, and a tolerable administration of justice.”
That phrase should not be read narrowly as an observation about courts.
A tolerable administration of justice means that rules are intelligible. That contracts can be enforced. That decisions are not reversed arbitrarily after capital has been committed. That regulatory processes can be navigated without ruinous delay or political favour. That businesses can resolve disputes without treating litigation, lobbying or uncertainty as a permanent cost of doing business.
In modern terms, Smith was describing an investable operating environment.
The lesson of Europe’s towns
Smith’s account of feudal Europe provides a revealing historical illustration.
In the feudal order, agricultural producers often had little incentive to improve their output. Property was insecure, mobility was restricted and power was concentrated in the hands of those able to extract much of any additional production. Producing more did not necessarily make a person more secure or prosperous; it could simply make them a more attractive target.
The political economist Barry Weingast has described this condition as a “violent, low-growth feudal equilibrium.” The important point is that it was stable precisely because insecurity made productive effort less rational.
The escape began in Europe’s commercial towns.
Kings wanted revenue, allies and a counterweight to powerful barons. Townspeople wanted rights, local self-government, security and the capacity to defend their commerce. A political bargain emerged: towns provided taxes and support; rulers granted liberties, legal protections, trading rights and a degree of autonomy.
The result was not a utopia. It was something more economically consequential: merchants and producers gained enough confidence to plan.
They could invest in workshops, warehouses, ships and commercial relationships. They could specialize for markets beyond the village. They could accumulate capital because they had greater reason to believe that its returns would not simply be seized, destroyed or arbitrarily redistributed.
Smith’s point was not that trade alone created prosperity. Commerce became transformative when institutions gave people confidence that the gains from cooperation would be sufficiently secure.
That is the historical insight Canada should bring to its relationship with Europe.
The real cost of uncertainty
Canada is not feudal Europe. It is an advanced democracy with a capable legal system, a skilled workforce and deep commercial relationships.
Yet Smith’s fundamental question remains relevant.
A company considering a critical-minerals refinery, defence-production facility, data centre, transmission line, port expansion, advanced-manufacturing plant or energy project does not invest in a political declaration. It does not invest in a treaty title. It invests in an expected return over years or decades.
That expected return depends on practical questions:
- Can approvals be obtained on a credible timetable?
- Are environmental, carbon, procurement and investment rules clear before capital is committed?
- Can the business obtain reliable power, transport, digital infrastructure, skilled labour and housing?
- Will its products have access to a sufficiently predictable market?
- Will the regulatory framework remain broadly stable over the life of the asset?
- If something goes wrong, is there a fair and functional way to resolve the dispute?
Tariffs are only one cost of commerce. Uncertainty is another – and, for long-lived investment, it may be the more expensive one.
This is why Canada’s European opportunity should not be defined as a search for an institutional label. It should be defined as an effort to reduce the uncertainty that discourages productive investment across the Atlantic.
That agenda would complement, not replace, Canada’s indispensable North American relationship. Canada’s economic integration with the United States remains profound and advantageous. But concentration also carries risk when trade policy, procurement preferences, national-security assumptions or political relationships change abruptly.
Diversification is not rejection.
It is insurance.
CETA is the floor
The Canada–EU Comprehensive Economic and Trade Agreement (CETA) remains a substantial asset. Provisionally applied since September 2017, it has removed most tariffs and created meaningful commitments on services, temporary entry, procurement and regulatory cooperation.
Its results matter. The European Commission reports that bilateral goods trade reached €81.5 billion in 2025, while combined goods-and-services trade reached €130 billion. Goods trade has expanded sharply since CETA’s provisional application.
But those figures should be understood correctly.
They show that CETA has created value. They do not show that the work is complete.
CETA has lowered barriers, but it is not a complete economic architecture for an era in which economic security, strategic supply chains, resilient energy systems, critical minerals, defence capacity, data governance and technological leadership matter as much as conventional trade flows.
Nor is CETA’s political implementation complete. Most of the agreement is provisionally applied, but it will only enter fully into force when all EU member states complete their national ratification procedures. As of 2026, 17 member states had notified ratification, with 10 still outstanding.
That does not diminish CETA. It clarifies the challenge.
Political goodwill is easier to announce than to translate into binding commitments that work across different national interests, legal systems and industrial constituencies. The next stage of the Canada–EU relationship should therefore focus on the barriers that remain after tariffs are lowered: procurement access, regulatory duplication, skills recognition, trusted technology rules, investment certainty and strategic supply-chain resilience.
CETA is the floor.
The task now is to build the institutional confidence that allows more projects to rise above it.
A test for the new alliance
Canada should welcome the proposed Alliance for the Future but insist that its success be assessed through commercial outcomes rather than institutional grandeur.
The test is not whether a new relationship sounds historic in Strasbourg.
The test is whether it enables a Canadian firm to bid, build, hire, finance, insure and export more predictably in Europe – and enables European capital and firms to do the same in Canada.
A serious Canada–EU agenda should focus on five practical areas.
First, trusted capital: transparent investment-screening rules, credible co-investment platforms and stable frameworks for energy, infrastructure, critical-mineral processing, digital capacity and advanced manufacturing.
Second, trusted production: reciprocal and security-conscious access to defence, resilience and strategic procurement, so that Canadian industrial capability can serve allied demand without becoming dependent on one national market.
Third, trusted standards: proportionate mutual recognition for professional qualifications, product testing, technical standards and carbon-accounting approaches – reducing duplication without requiring Canada simply to import European rules.
Fourth, trusted innovation: workable arrangements for research collaboration, data, artificial intelligence, cybersecurity, quantum technologies and intellectual property that help turn research partnerships into companies, supply chains and exportable products.
Fifth, trusted people: selective and reciprocal mobility for researchers, students, entrepreneurs, scarce skilled workers and temporary project teams – designed around real economic needs, not open-ended labour-market integration.
This is not an argument for rule-taking.
Canada should not exchange policy autonomy for a vague badge of geopolitical alignment. Nor should it treat regulatory convergence as an end in itself. Canadian interests in energy, agriculture, industrial policy, procurement and labour-market capacity will not always align with European priorities.
That is not a failure of partnership.
It is the substance of negotiation.
Trust does not mean the absence of rules. It means confidence that rules are clear, reciprocal, proportionate and durable.
The measure of success
The European Commission’s proposal is important because it acknowledges a changing world.
Canada and Europe face a common strategic challenge: how to remain open economies while reducing exposure to coercion, concentrated dependencies and sudden political disruption. The answer is not autarky. It is a broader network of trusted commercial relationships among democratic partners able to trade, invest and innovate with confidence.
Adam Smith understood that prosperity depends on more than the freedom to exchange. It depends on the institutional conditions that make cooperation rational.
Canada’s European opportunity, therefore, is not to acquire a new identity.
It is to help construct a dependable economic operating system across the Atlantic – one that gives firms more confidence to invest, gives workers more opportunities to develop valuable skills, gives researchers a clearer route to commercial impact, and gives Canada more options in an increasingly uncertain world.
The Vimy Oaks are a fitting metaphor. History can plant the acorn. Shared values can protect the sapling. Diplomacy can create the conditions for growth.
But only trusted institutions allow a relationship to take root, endure and bear fruit.
A diplomatic announcement can attract attention.
A trade agreement can lower tariffs.
Trusted institutions are what turn opportunity into growth.
Dr Brian O’Donnell is Founder and Principal of Aurex Insights, an independent economic-policy and strategic-advisory practice working between Ireland and Canada. He advises organisations on enterprise policy, industrial strategy, fiscal analysis, legislative engagement and Canada–Europe economic relations.