Submissions close December 3, 2026. For charity leaders, this is an opportunity to bring practical evidence into decisions about how the sector is regulated – and develop a policy position that remains useful beyond the deadline.
By Dr. Brian O’Donnell, DBA
Principal & Founder, Aurex Insights
A charity’s most valuable contribution to a policy review may begin with an everyday operational experience: difficulty accessing a digital account, uncertainty about a reporting requirement, a prolonged registration process or correspondence that leaves important questions unanswered.
Individually, these can appear to be administrative frustrations. Taken together, they can reveal where a regulatory framework works well – and where it needs to change.
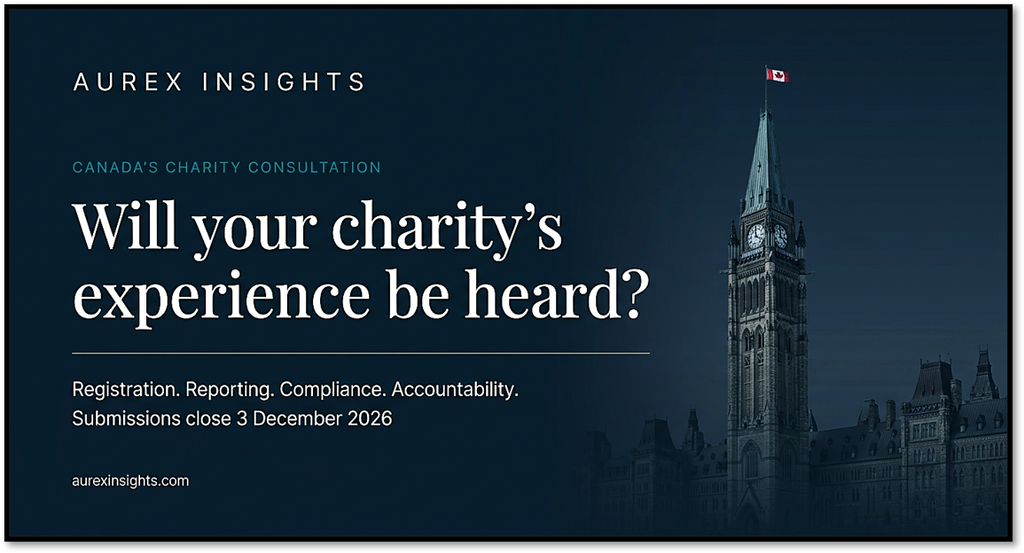
On October 8, the Department of Finance Canada and the Canada Revenue Agency launched a consultation on modernising the federal framework for registered charities. Submissions close on December 3, 2026. The review covers registration, digital service delivery, audit and compliance, and revocation and objections.
For charity leaders, the immediate question is not whether their organisation can answer every question in the consultation.
It is whether their experience can help government make better decisions – and whether that experience will otherwise be heard.
Administrative rules affect the resources available for charitable work
Canada has more than 86,000 registered charities delivering services, supporting communities and advancing charitable purposes at home and abroad. The wider non-profit sector is also economically significant: non-profit institutions contributed approximately C$244 billion to GDP in 2024, representing 8.4% of the national economy and supporting more than 2.5 million jobs. These economic figures relate to non-profit institutions, not exclusively to registered charities.
Effective oversight matters. Tax-assisted donations must serve charitable purposes, and the public must have confidence that organisations meet their obligations.
But the way those obligations are administered also matters.
An unclear requirement can consume management time. An inaccessible digital process can turn a routine task into a recurring problem. Regulatory uncertainty can complicate planning and draw attention away from service delivery.
The objective should not be less accountability. It should be a framework that combines clear obligations, accessible administration and proportionate enforcement.
That balance is central to the consultation.
What the government is reviewing
The consultation opportunity brings together four areas that charities may usually encounter separately Consultations on Modernizing the Framework for the Charitable Sector – Canada.ca.
- Registration: whether guidance, application processes and decision-making are sufficiently accessible, understandable and transparent.
- Digital services and reporting: whether charities can use CRA systems reliably, maintain accurate contact information and submit complete, consistent and timely annual returns.
- Audit and compliance: how the CRA supports voluntary compliance, applies penalties and suspensions, and maintains confidence in procedural fairness.
- Revocation and objections: how charitable status can be withdrawn, how decisions can be challenged and whether existing processes provide an appropriate balance between fairness and timely enforcement.
The review goes beyond making existing processes easier to use. It asks whether intermediate sanctions should be used more widely, how much information about serious non-compliance should become public, and whether objection timelines should change. It also examines safeguards around asset transfers following revocation and the circumstances in which an organisation should be permitted to re-register.
These questions concern both sides of an effective framework: reducing unnecessary burdens and protecting regulatory integrity.
Why operational evidence matters
Consider digital reporting. The consultation paper states that just under 31% of T3010 annual returns were submitted electronically in 2025–26, despite online filing being available. It asks what prevents greater uptake and what support would help charities use digital services confidently.
That figure does not explain the barriers. Charities’ experience can.
The same is true of late filings, registration difficulties and compliance processes. A policy document can identify a question; organisations dealing with the system can explain its practical consequences.
The government is also asking whether failure to file an annual return should continue to result in revocation, or whether monetary penalties or suspension could be more appropriate. The paper reports 1,219 revocations for failure to file in 2025–26.
Assessing those alternatives requires more than a general preference for lighter administration. It requires an understanding of why failures occur, what encourages compliance and how public confidence can be preserved.
That is where thoughtful contributions from the sector can add value.
Should your organisation make its own submission?
Not every charity needs a separate response.
National associations and umbrella bodies can provide valuable collective representation. Contributing through an existing sector process may be the most proportionate option, particularly where the organisation’s concerns are already well understood.
An individual or collaborative submission becomes more valuable when an organisation has distinctive evidence: a recurring administrative difficulty, an experience shaped by its operating model or community, or a practical improvement that broader representations may not capture.
A sector body can establish that a concern is widespread. An organisation can show how it arises and what a workable remedy would need to address.
The decision should therefore turn on the contribution available – not on an assumption that every charity must participate.
A focused response on one important issue may be more useful than a lengthy document commenting generally on the entire framework.
A credible submission requires judgement, not simply drafting
The challenge for many charities is not a shortage of relevant experience. It is finding the capacity to turn that experience into a coherent organisational position.
Knowledge may be spread across finance, operations, leadership and the board. Relevant evidence may sit in correspondence, records or the recollections of staff already carrying substantial responsibilities.
A persuasive response must distinguish an isolated difficulty from a wider policy problem. It should recognise legitimate regulatory objectives while explaining where administration could work better.
The strongest case is not simply that a change would make life easier for one organisation. It is that the change could improve effectiveness, fairness or accountability while protecting the public interest.
Bringing those elements together is substantive policy work – not merely an exercise in producing a document.
The value can extend beyond December 3
A well-developed submission can become a foundation for continued engagement.
Over the following six months, the organisation could draw on its approved evidence and recommendations to brief its board, contribute to association discussions and inform appropriate conversations with policymakers.
The work may also identify wider funding or service-delivery concerns that deserve separate attention.
Those issues should not be forced into this consultation. Its scope is the federal tax framework for registered charities and its administration – not a general review of charity funding or government spending priorities.
A disciplined response stays within that scope. Related concerns can then be developed into separate briefings for the relevant audience.
There is no guarantee that government will adopt a recommendation, and the submission deadline does not establish a timetable for subsequent decisions. Nevertheless, an approved, evidence-led position can remain useful long after the consultation closes.
Why the decision should be made now
December 3 is the government’s deadline. An organisation’s practical deadline may be earlier.
Staff may need to be consulted, evidence checked and recommendations agreed. Some organisations will also require board consideration.
Beginning early creates room for that judgement and review. Leaving the decision until late November risks making participation dependent on whoever happens to have time.
The immediate task is to establish whether the organisation has a meaningful contribution to make, whether it is already represented elsewhere and what level of participation is proportionate.
How Aurex Insights can help
Aurex Insights is accepting a small number of assignments to help charities, foundations and sector bodies assess the consultation, develop their strongest evidence and prepare clear, approval-ready responses.
The process is designed to limit demands on management while preserving the organisation’s ownership of its recommendations and final approval. Scope, timetable and fees are agreed before paid work begins.
This sits within Aurex’s broader support for organisations seeking to articulate their economic and public value, develop credible policy positions and make stronger cases for sustainable funding. That work can support engagement with federal and provincial governments in Canada, and national government, public agencies and other funders in Ireland.
For this consultation, a complimentary, confidential 20-minute initial discussion can help determine whether an individual response is worthwhile – or whether a collaborative or umbrella route would be more appropriate.
Organisations considering submission support are encouraged to contact Aurex as soon as possible, allowing time for evidence gathering, drafting and internal approval. Later assignments will depend on scope and capacity.
Request a free 20-minute consultation https://aurexinsights.com/contact/#Booking-form
To discuss whether your organisation has evidence worth contributing, contact:
Brian@aurexinsights.com
aurexinsights.com
Dr Brian O’Donnell is Founder and Principal of Aurex Insights, an independent economic-policy and strategic-advisory practice working between Ireland and Canada. He advises businesses, charities and sector organisations on policy strategy, economic and public-value propositions, and evidence-led engagement with governments and funders. His wider work includes Canada–Europe economic relations and organisational strategy.
This article provides general public-policy information and does not constitute legal, tax or accounting advice. Organisations requiring advice on their specific obligations should consult an appropriately qualified professional.